Key takeaways
- The equipment secures the loan, so it is often easier to qualify for than an unsecured loan.
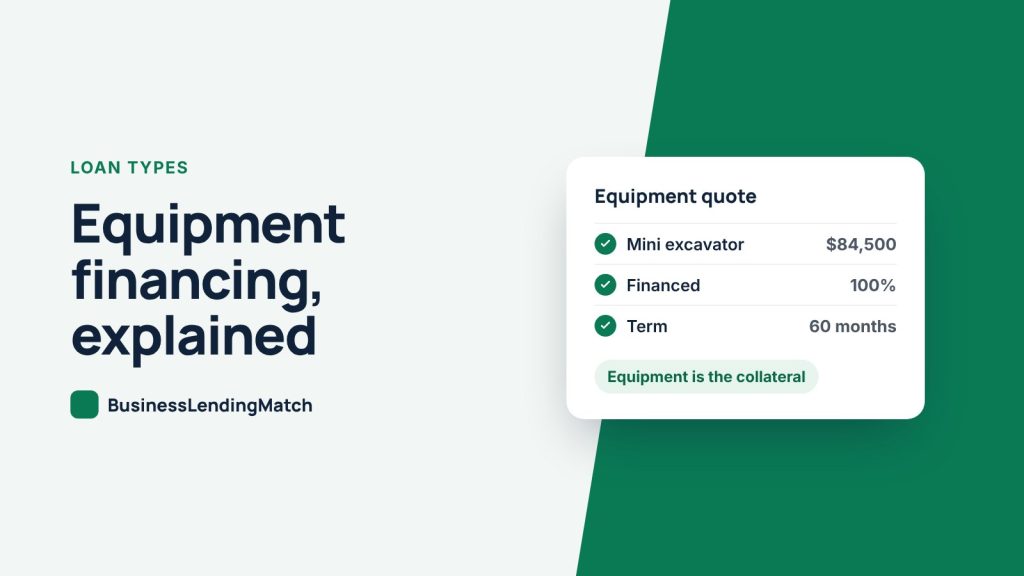
- Many lenders finance 80% to 100% of the price with terms matched to the equipment’s useful life.
- New and used equipment both qualify. A loan builds ownership; a lease can keep payments lower.
Equipment financing is a loan or lease used to buy business equipment, where the equipment itself is the collateral. Because the lender can recover the equipment, approvals are often easier and faster than for unsecured loans. Lenders commonly finance 80% to 100% of the price over 2 to 10 years, depending on what you buy and your credit.
What equipment financing covers
Almost anything with a resale value: construction machinery, trucks and trailers, restaurant kitchens, medical and dental equipment, manufacturing machines, technology and vehicles. Many lenders also finance used equipment and private-party purchases, sometimes with shorter terms.
Typical terms
| Typical range | |
|---|---|
| Amount financed | 80% to 100% of the price |
| Term | 2 to 10 years, matched to the equipment’s useful life |
| Credit score | Often 600 to 650+, lower with a down payment |
| Time in business | Often 1 to 2 years, some programs for startups |
| Speed | A few days for most purchases |
Loan or lease?
- Equipment loan: you own the equipment and build equity. Best for long-lasting equipment.
- Fair market value lease: lower payments and the option to return or upgrade at the end. Good for technology that ages fast.
- $1 buyout lease: works much like a loan, you own it at the end for $1.
Ask your accountant how each option affects your taxes. Equipment purchases may qualify for Section 179 or bonus depreciation, with limits that change from year to year.
How to get approved fast
- Get a written quote or invoice from the dealer or seller, including the serial number for used equipment.
- Have 3 to 6 months of bank statements ready.
- For larger amounts, have your last 2 years of tax returns.
- Know how the equipment will pay for itself: more jobs, lower rental costs or less downtime.
When another loan type fits better
If you are also covering payroll or materials, a working capital loan or line of credit may make sense alongside equipment financing. For large purchases with 2+ years in business, compare SBA 504 and SBA 7(a) loans.
Frequently asked questions
Can I finance used equipment?
Yes. Many lenders finance used equipment, though older equipment may get shorter terms or need a down payment.
Do I need a down payment?
Not always. Strong credit can get 100% financing. With lower credit, expect 10% to 20% down.
Can a new business get equipment financing?
Some lenders have startup programs, usually with strong personal credit and a down payment.
Get matched with an equipment lender
Equipment lenders specialize: some focus on trucks, others on medical or construction equipment. Tell us what you are buying and we will match you with the vetted lender that finances it best. Get a Loan.