Key takeaways
- A merchant cash advance buys a share of your future sales and is repaid daily or weekly.
- Factor rates look small, but the effective APR is often well above 50%.
- Use an advance only for short, high-return needs, and only if a loan is not available.
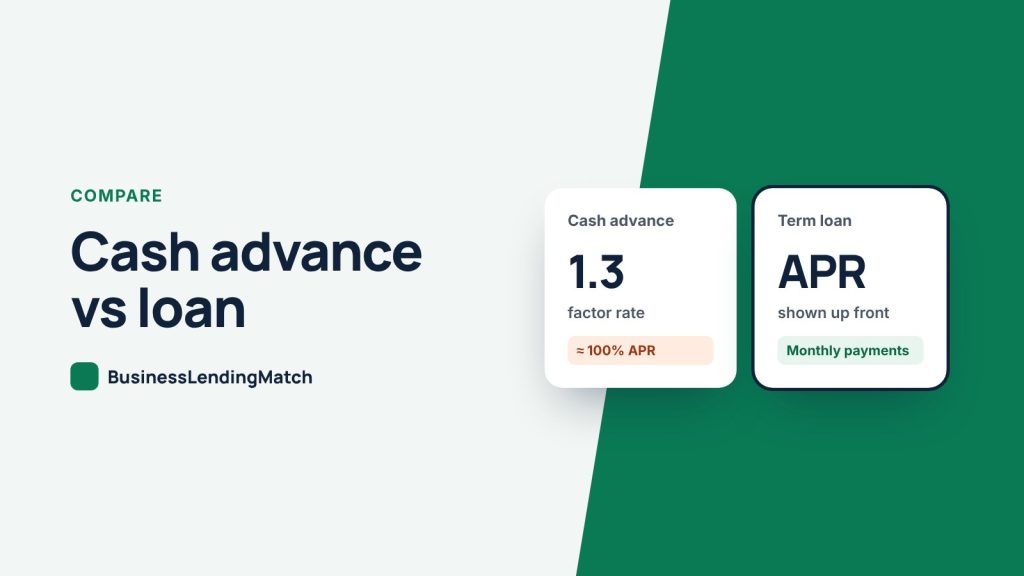
A business loan charges interest over a set term. A merchant cash advance (MCA) gives you cash now in exchange for a fixed amount of your future sales, repaid through daily or weekly withdrawals. Advances are faster and easier to qualify for, but usually far more expensive: a factor rate of 1.3 repaid over six months can work out to an APR of around 100%.
How each one works
| Business loan | Merchant cash advance | |
|---|---|---|
| What it is | Borrowed money with interest | Purchase of future sales |
| Cost shown as | Interest rate or APR | Factor rate, such as 1.25 |
| Payments | Usually monthly | Daily or weekly |
| Paying early | Often saves interest | Usually saves nothing |
| Qualifying | Credit, time in business, cash flow | Mostly steady card or bank deposits |
| Speed | Days to weeks | Often 1 to 2 days |
A worked example
You take a $50,000 advance at a 1.3 factor rate. You repay $65,000, so the cost is $15,000. If it is paid back through daily withdrawals over about six months, you have the full $50,000 for only a short time before payments start shrinking your balance. That pattern is why the effective APR lands near 100% even though “1.3” sounds modest.
Compare that with a $50,000 term loan at a moderate rate over two years. The monthly payment is higher than one daily payment looks, but the total cost can be a fraction of the advance.
Several states, including California and New York, now require many commercial financing providers to show an estimated APR. If an offer does not show one, ask for it.
When a cash advance can make sense
- A short, high-return opportunity, such as a bulk inventory discount you can resell quickly
- An urgent gap when you do not qualify for a loan or line of credit
- Businesses with high card sales and short-term needs
When to avoid one
- Covering ongoing losses or long-term costs
- Paying off another advance (stacking)
- When you qualify for a line of credit or working capital loan
Already have advances? Consider refinancing
If daily payments are squeezing your cash flow, debt refinancing can combine advances into one longer-term loan with a lower payment, if your revenue and credit support it.
Frequently asked questions
Is a merchant cash advance a loan?
Usually not legally. It is a sale of future receivables, which is why it is not always covered by lending rules.
What is a good factor rate?
Factor rates commonly range from about 1.1 to 1.5. Lower is better, but always convert it to total cost and APR before comparing.
Can I pay off an MCA early to save money?
Usually not. The payback amount is fixed, though some providers offer an early payoff discount. Ask before you sign.
See if you qualify for a lower-cost loan first
Many owners take an advance because it is the first offer that calls back. Tell us about your business and we will match you with the vetted lender offering the best fit for your profile, which is often a loan, not an advance. Get a Loan.