Key takeaways
- SBA Express goes up to $500,000 and is faster because the lender makes the decision itself.
- Standard SBA 7(a) goes up to $5 million with a larger government guarantee, so lenders can approve more.
- Both offer long terms and capped rates. Pick Express for speed under $500K, standard 7(a) for size.
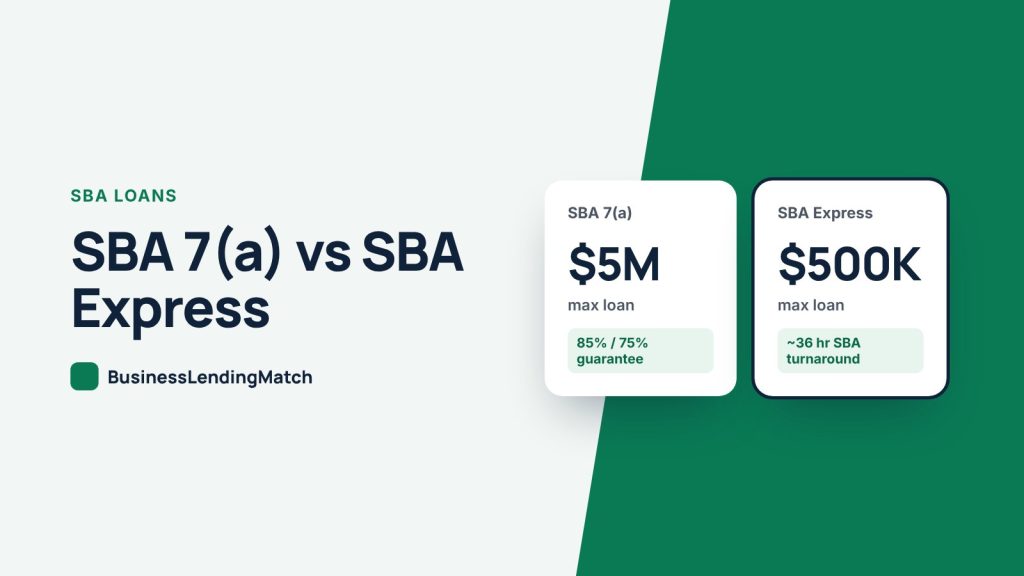
SBA Express is the faster option for loans up to $500,000, because approved lenders make the credit decision themselves and the SBA responds within about 36 hours. Standard SBA 7(a) loans go up to $5 million and carry a bigger government guarantee, which helps lenders approve larger or harder deals, but they usually take longer. Here is how they compare.
Side by side
| Standard SBA 7(a) | SBA Express | |
|---|---|---|
| Maximum loan | $5 million | $500,000 |
| SBA guarantee to the lender | 85% up to $150K, 75% above | 50% |
| Who decides | Lender and SBA (or lender with delegated authority) | Lender |
| SBA turnaround | Varies, often days to weeks | About 36 hours |
| Terms | Up to 10 years for most uses, 25 for real estate | Same, plus revolving lines of credit |
| Rates | Both capped by the SBA as a markup over the prime rate | |
Program limits and fees change. Confirm current figures with your lender or at sba.gov before you apply.
When SBA Express is the better pick
- You need $500,000 or less.
- Speed matters more than squeezing out the lowest possible rate.
- You want a revolving line of credit with SBA terms.
- Your file is straightforward: solid credit, 2+ years in business and clear cash flow.
The trade-off: with only a 50% guarantee, lenders take on more risk, so Express approvals tend to go to stronger files.
When standard SBA 7(a) is the better pick
- You need more than $500,000, up to $5 million.
- You are buying a business, refinancing debt or buying real estate along with other uses.
- Your file needs the extra guarantee to get approved, such as a newer business with a strong plan.
Learn more on our SBA 7(a) loans and SBA Express loans pages. Buying property or major equipment? Also compare SBA 504 loans.
What both require
- A for-profit business in the U.S. that meets SBA size standards
- A personal guarantee from every owner with 20% or more
- Showing the business can repay from cash flow
- No current delinquencies on federal debt
Most SBA lenders also look for personal credit around 650 to 680 or higher and two years of tax returns.
How to get either one faster
The biggest delay in SBA lending is not the SBA, it is the back and forth over missing documents and lenders that turn out not to do your kind of deal. Have your last two years of tax returns, year-to-date financials, a debt schedule and a personal financial statement (SBA Form 413) ready, and work with a lender that regularly closes SBA loans for businesses your size.
Frequently asked questions
Is SBA Express easier to get than a 7(a) loan?
It is faster, not easier. Because the guarantee is only 50%, lenders usually reserve Express for strong applications.
How long does a standard SBA 7(a) loan take?
Plan on several weeks from application to funding, longer for real estate or business acquisitions.
Can I use SBA Express for working capital?
Yes. Working capital, equipment, inventory and refinancing are all common uses, and Express can be set up as a revolving line.
Find the right SBA lender
Not every bank does SBA loans, and the ones that do have different sweet spots. Tell us about your business and we will match you with the vetted SBA lender most likely to approve your request. Get a Loan.