Key takeaways
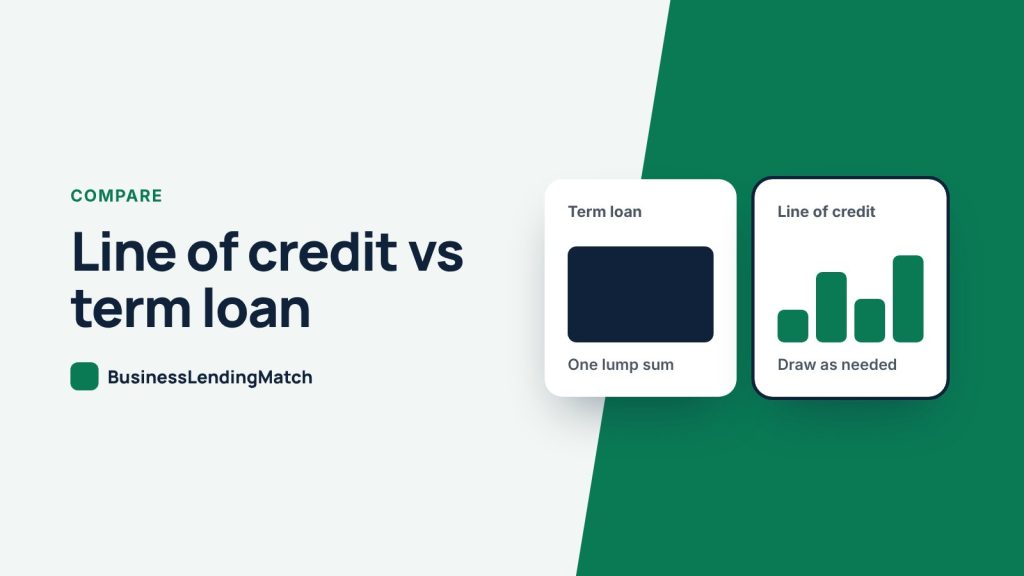
- A term loan gives you a lump sum for a one-time cost and is repaid on a fixed schedule.
- A line of credit lets you draw as needed and pay interest only on what you use.
- Use a term loan to buy or build something. Use a line of credit to smooth out cash flow.
Choose a term loan when you need a set amount for a one-time investment, such as equipment, an expansion or buying a business, and want a predictable payment. Choose a business line of credit when your cash needs come and go, such as seasonal slowdowns, payroll gaps or slow-paying customers, because you only pay interest on what you draw.
How each one works
| Term loan | Line of credit | |
|---|---|---|
| How you get money | One lump sum | Draw any amount up to your limit |
| Interest | On the full balance from day one | Only on what you have drawn |
| Repayment | Fixed payments over a set term | Pay down and draw again |
| Typical size | Larger | Smaller, often a share of monthly revenue |
| Best for | Planned, one-time costs | Ongoing or unpredictable costs |
When a term loan makes sense
- Buying equipment, vehicles or another business
- Opening or renovating a location
- Refinancing expensive debt into one payment
- Any cost with a clear return over time
See how term loans work, or compare SBA 7(a) loans if you have 2+ years in business and want the lowest rate.
When a line of credit makes sense
- Covering payroll while you wait on customer payments
- Buying inventory ahead of a busy season
- Keeping a cushion for repairs or surprise costs
- Taking on a big job before the first invoice is paid
Learn more about business lines of credit. If slow-paying invoices are the main problem, invoice factoring may be a better fit.
What they cost
Term loans usually carry a fixed rate and sometimes an origination fee. Lines of credit may have a variable rate plus draw fees or a yearly fee. A line of credit can cost less overall when you only use it occasionally. A term loan usually costs less when you need the whole amount for a long time. Ask each lender for the APR and the total cost so you compare on the same basis.
Can you have both?
Yes, and many growing businesses do: a term loan for the big purchase and a line of credit for working capital. Lenders will look at the combined payments when you apply for the second one.
Frequently asked questions
Is a line of credit easier to get than a term loan?
Smaller lines of credit from online lenders can be easier to qualify for. Larger bank lines usually need strong financials and sometimes collateral.
Does an unused line of credit cost anything?
Some lines charge a yearly or maintenance fee even when unused. Many charge nothing until you draw.
Which is better for a new business?
Newer businesses often start with a smaller line of credit or equipment financing, then move to larger term loans once they have two years of history.
Get matched with the right one
Tell us what the money is for and we will match you with the vetted lender that offers the right product for it. Get a Loan.